Visa and Mastercard asked a U.S. court on Monday (16) to grant final approval to a settlement that could generate savings of US$ 38 billion for merchants through 2031. The proposal calls for reducing interchange fees on credit card payments and changes to the rules determining which cards businesses can accept.
Federal Judge Brian Cogan, who is overseeing the case in New York, ended the hearing without announcing a decision. The settlement covers more than 12 million merchants and seeks to resolve an antitrust dispute that began in 2005.
The savings estimate was prepared by economists Joseph Stiglitz, winner of the Nobel Prize in Economics, and Keith Leffler, a professor at the University of Washington, hired by the plaintiffs. The amount corresponds to projected reductions in future expenses, not a financial damages payment.
The proposal establishes a reduction of 0.1 point in the average effective interchange rate, in percentage points, over five years, in addition to capping the posted rates on standard consumer credit cards at 1.25% for eight years.
According to the Merchants Payments Coalition, Visa and Mastercard interchange fees in the United States totaled US$ 118.8 billion in 2025.
Settlement will allow merchants to reject certain categories of cards
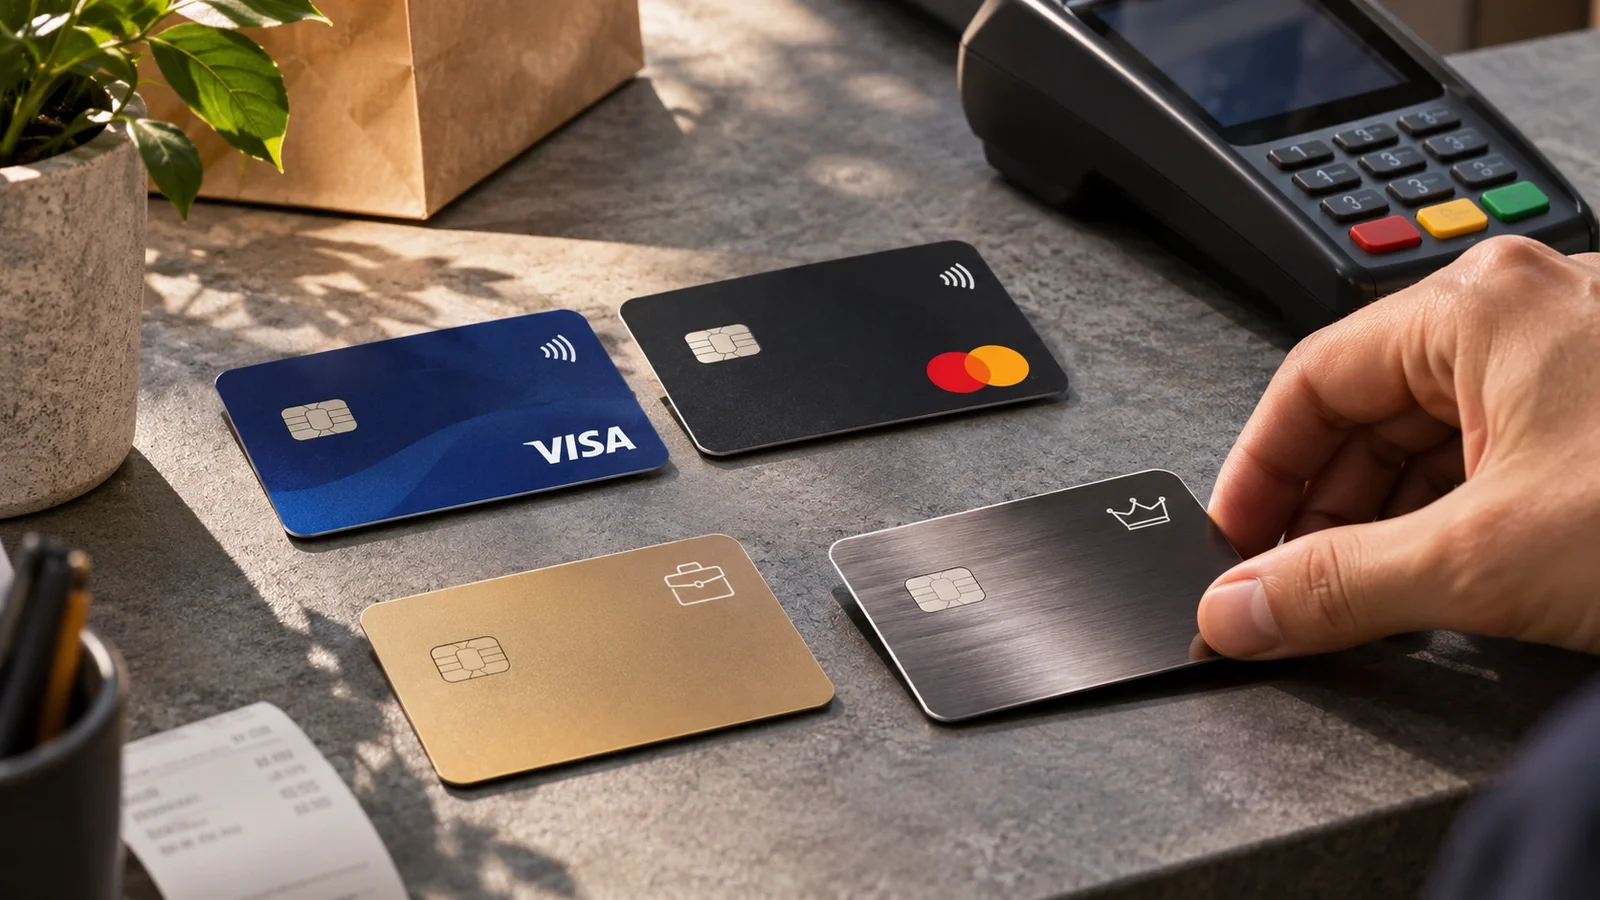
One of the main changes involves the rule known as Honor All Cards, which requires businesses to accept all credit cards from a given network if they choose to work with it.
Under the terms published on the settlement's official website, merchants will be able to choose among three categories: corporate cards, standard cards and premium cards, including products that offer benefits such as cashback and miles.
A business could, for example, accept Visa standard cards and reject the same network's corporate cards, while adopting different criteria for Mastercard.
The proposal also expands the possibilities for charging additional fees on credit card payments and allows online stores to choose which digital wallets to offer consumers, subject to certain conditions.
The changes, however, have not eliminated resistance from major retailers. The court received more than a thousand objections, including filings from Walmart and the National Retail Federation.
Among the main criticisms are keeping high fees for premium cards and the impossibility of selecting cards individually according to the issuing bank. The popularity of rewards programs also makes it difficult to reject these products without affecting the consumer experience.
The settlement received preliminary approval in June 2026. If final approval is denied, Cogan indicated that the case could proceed to trial in 2027.