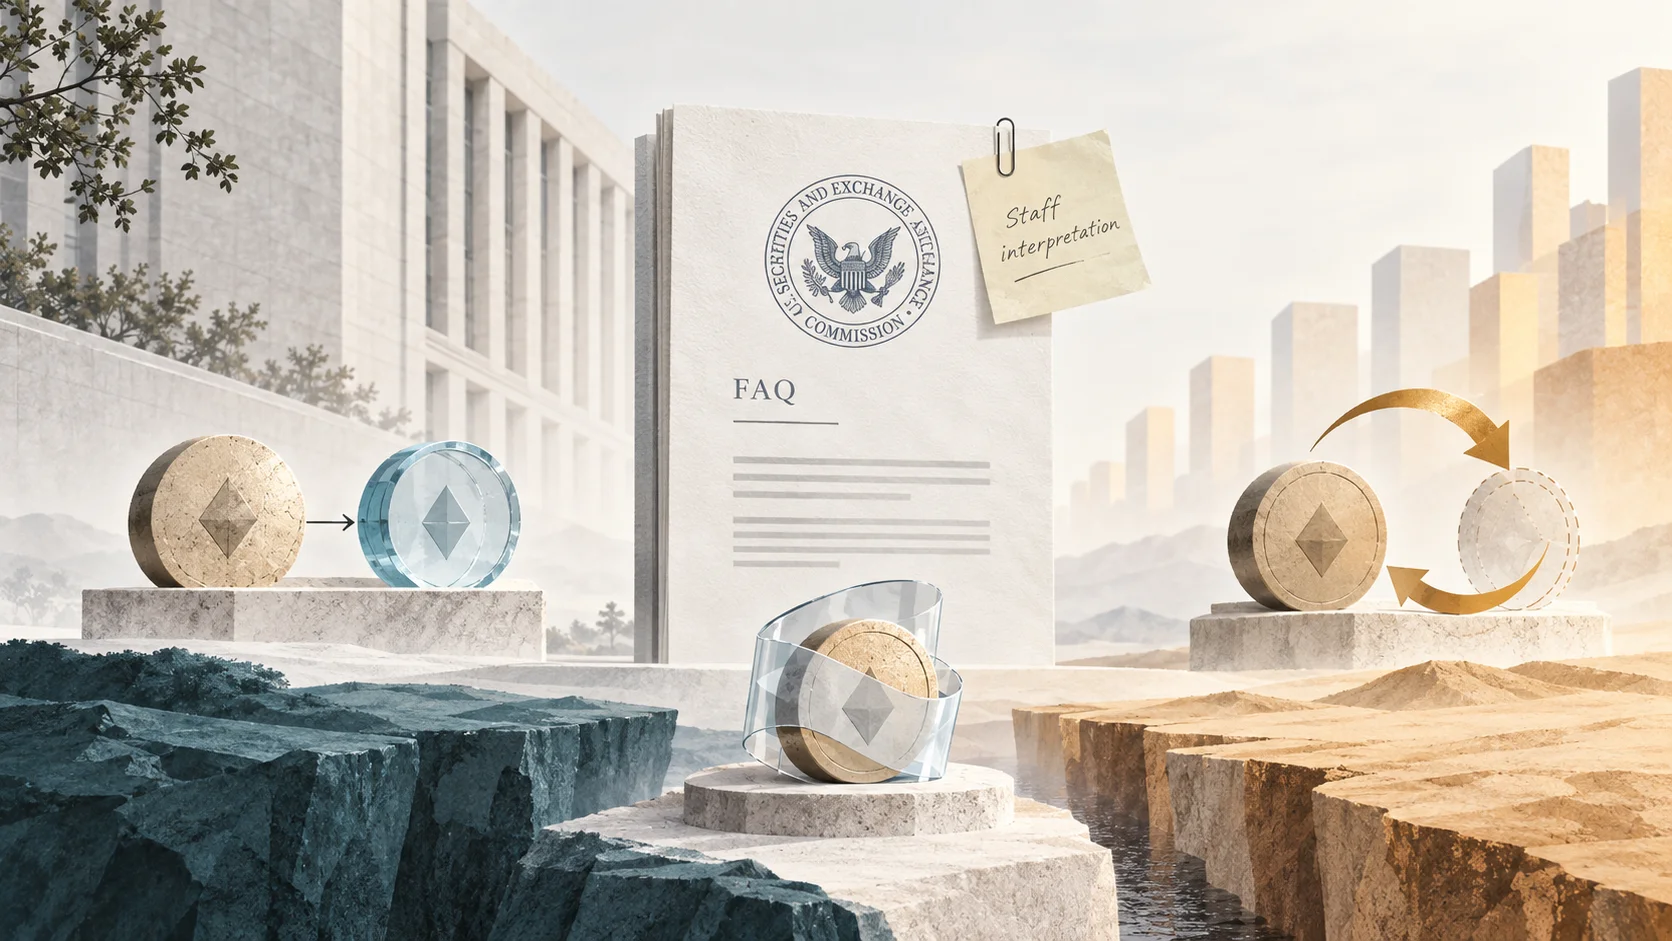
The staff of the SEC's Division of Corporation Finance published on Friday (25) nine new questions and answers on how U.S. federal securities laws apply to different structures with crypto assets, including staking receipt tokens, wrapped tokens, token buybacks and trading in secondary markets. The document, however, does not create a new rule or new legal obligations.
The SEC itself emphasizes that the answers represent exclusively the view of the division's staff and were neither approved nor rejected by the Commission. The FAQs detail how the agency interprets specific situations within the framework presented by the SEC in March of this year.
Among the main clarifications is the treatment of staking receipt tokens. According to the staff, a token that merely represents ownership of a deposited digital asset can be classified as a digital tool when the underlying asset is not subject to an investment contract. In certain protocol-based liquid staking structures, the receipt token can also be considered a digital commodity.
To be treated as a simple “receipt,” the instrument must not create additional financial rights or incentives. The issuer also cannot use the deposited asset for loans, collateral, rehypothecation or other operations. The definition is also relevant for structures such as redeemable wrapped tokens.
Buybacks depend on the stage of the network
The SEC also detailed how buyback programs can be analyzed under the Howey test. In an already functional network, the announcement of a buyback of a crypto asset that is not a security would not, by itself, be a promise of essential managerial efforts.
The situation changes when the system is not yet functional. In that case, a buyback can contribute to characterizing a promise relevant to the Howey test if the issuer presents the operation as a way to generate yield or return for token holders.
The FAQs also indicate that maintenance, security, technical improvements and initiatives aimed at expanding the network effects of an already functional system are generally not considered essential managerial efforts. Likewise, disclosing current functionalities or discussing future features in aspirational terms tends not to be sufficient, in isolation, to create a promise tied to the expectation of profit. The SEC cautions that the assessment continues to depend on the facts and circumstances of each case.
Another point involves trading platforms. The existence of a secondary market for a given crypto asset does not automatically turn the platform into a promoter of the asset. For that, it would need to fall under the definition of “promoter” set out in Rule 405 of the Securities Act.
In practice, the document offers additional parameters for issuers, protocols, platforms and legal advisors to assess specific structures, but without replacing existing legislation or the formal rulemaking process by the SEC. The distinction is central: the FAQs explain the staff's current position, but do not have the force of law.