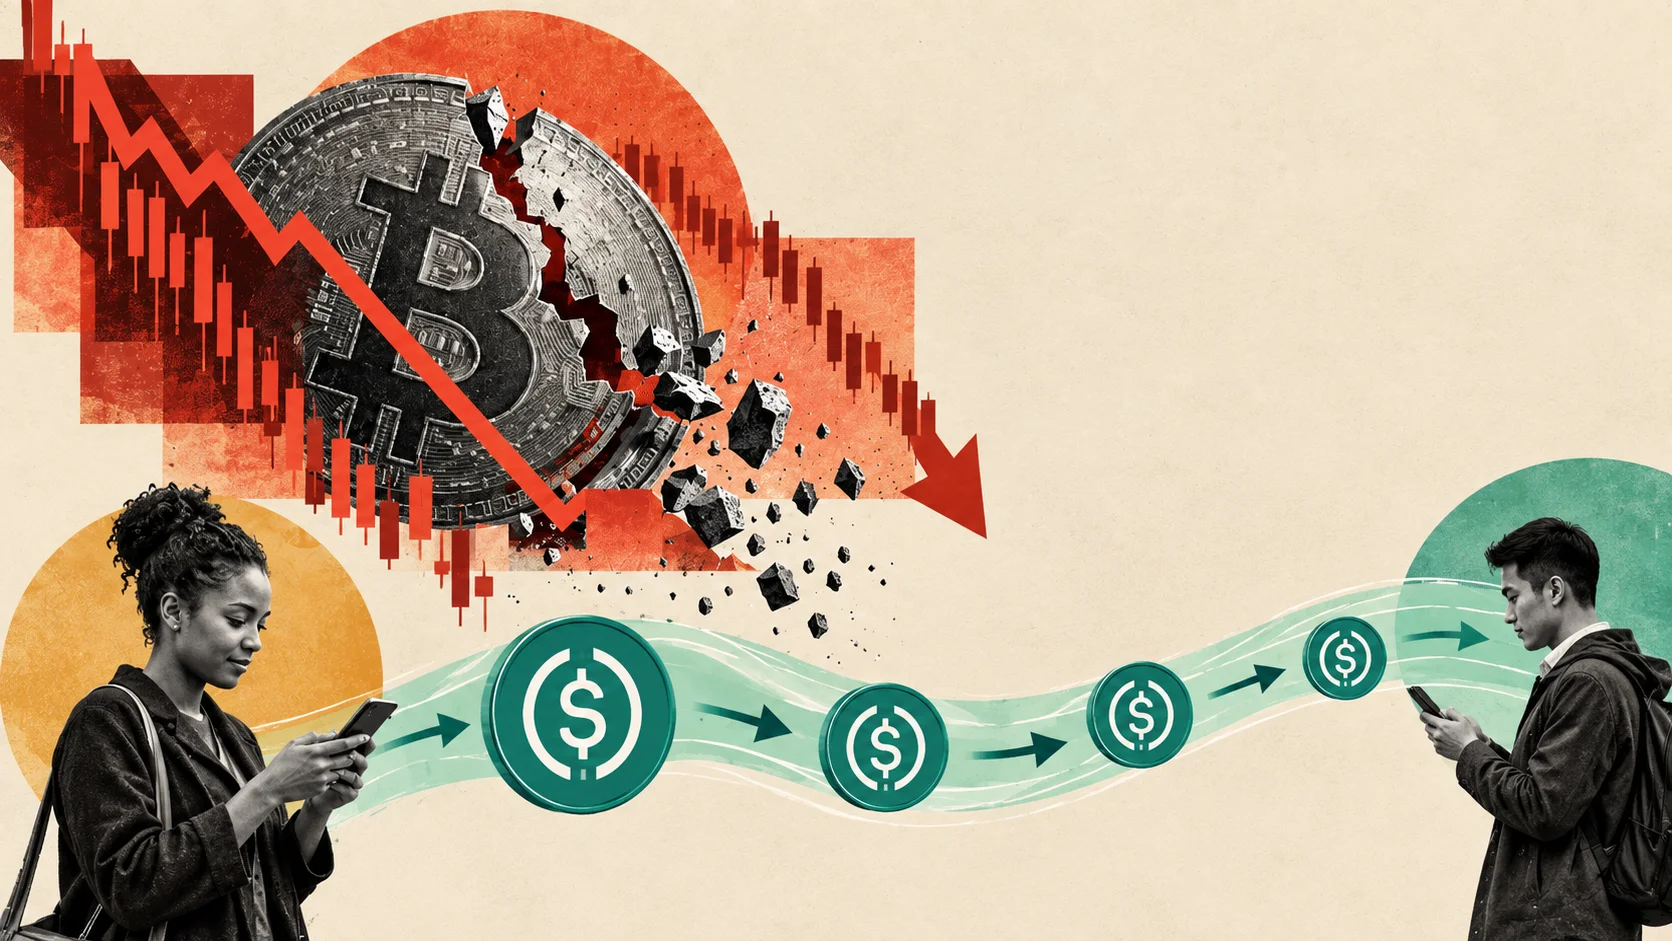
The cryptocurrency market lost about US$ 2.1 trillion in market capitalization between July 2025 and June 2026, a contraction of nearly 50%. In the same period, however, on-chain economic activity estimated by Chainalysis retreated only 1.6%, from US$ 9.5 trillion to US$ 9.4 trillion. The difference suggests that a growing part of the crypto economy is ceasing to depend directly on the appreciation of Bitcoin and other assets, with stablecoins and peer-to-peer transfers taking on a larger role in payments, remittances and the movement of digital dollars.
The shift appears more clearly when flows are separated. The value sent to exchanges, DeFi protocols and other services fell 4.3%. Domestic transfers directly between wallets, meanwhile, grew 302.9%, from US$ 56.8 billion to US$ 228.7 billion. At the same time, international stablecoin flows rose 77.5%, to US$ 220.3 billion.
The numbers do not mean that the crypto economy has become immune to market cycles. They indicate something more specific: the segment used to transfer value is proving to be less sensitive to price than the segment used primarily to trade assets.
Stablecoins begin to separate use from speculation
The difference lies in the mechanics of the transactions themselves.
When Bitcoin or another asset loses half its value, a transfer of the same amount of tokens comes to represent fewer dollars. Moreover, periods of decline tend to reduce speculative turnover. This effect appeared in flows directed to crypto services, which retreated during the period analyzed.
Stablecoins work differently. A transfer of US$ 1,000 in USDT or USDC continues to represent approximately US$ 1,000 regardless of Bitcoin's price. If the goal is to pay a supplier, send money to another country or hold a dollar-denominated balance, the need for the transaction also does not necessarily disappear because the market entered a downturn.
The data from Chainalysis reinforce this separation. Stablecoins already account for 96% of P2P activity measured by the company. While domestic P2P considering all assets fell 19.7%, its stablecoin share grew 377.7%. Even within traditional services, stablecoin flows rose 5.3% while the total retreated.
The same happened with balances. The global value of crypto assets held on-chain fell from US$ 860 billion in September 2025 to US$ 440 billion in June 2026. Stablecoin balances, however, remained in a relatively stable range, between US$ 98 billion and US$ 109 billion.
This behavior helps explain why the decline in activity was much smaller than the destruction of market value.
International transfers show a different economy
Cross-border flows provide a second piece of evidence that stablecoins are being used for functions that do not depend directly on speculation.
Chainalysis estimates that the monthly value identified in international stablecoin transfers went from approximately US$ 11 billion in January 2025 to US$ 24 billion in June 2026. The average value of these operations was close to US$ 3,000, a scale compatible with supplier payments, remittances and movement of savings, and not only with large institutional operations.
The company also identified 4,708 new international corridors of stablecoins during the period, responsible for US$ 2.64 billion in transfers. Its methodology is conservative: operations in which origin or destination cannot be safely associated with a country are left out of the calculation.
The International Monetary Fund already identifies the same movement from another angle. In 2026, the body stated that stablecoins surpassed unbacked crypto assets as the main instrument of cross-border crypto activity in emerging economies, although these flows still represent a small share of the global financial system. The IMF points to reduced friction and the potential for lower costs in international payments, but also risks of dollarization, capital flight and transmission of financial shocks.
This counterpoint is important. Growth within the crypto universe still does not equate to replacing traditional payment networks. The BIS estimated about US$ 390 billion in stablecoin flows effectively linked to payments in 2025, a small fraction compared with the global international payments system. Much of the gross volume of stablecoins is still linked to trading, arbitrage and other financial operations within the crypto ecosystem itself.
Brazil shows where this shift can gain scale
Brazil adds an important dimension to the trend. The country took 1st place in Chainalysis's new global adoption index, with an estimated crypto economy of US$ 252.5 billion. The result did not come from leadership in a single metric: Brazil ranked among the top four in total flows, balances, domestic P2P and international transfers.
More relevant to the analysis is the behavior of stablecoins. According to Chainalysis, Brazil's stablecoin economy grew 495%, versus 89.4% in the rest of Latin America. Stablecoin P2P transfers between US$ 10,000 and US$ 100,000 rose 562%, and those between US$ 100 and US$ 1,000 grew 666%.
The Brazilian pattern also shows that adoption does not necessarily mean paying for coffee in USDT. Pix already meets much of the need for instant domestic payments. Chainalysis points out that stablecoins in the country are gaining ground especially among companies, in liquidity, access to dollars and international transfers. The number of Brazilian wallets holding at least US$ 10,000 in stablecoins increased 347% since July 2024.
In Latin America as a whole, stablecoins reached in June 32.1% of the cross-border value measured by Chainalysis, 22.1% of domestic P2P and 17.6% of balances in personal wallets.
Bear market remains the most important test
The difference between capitalization and activity provides relevant evidence of maturation, but still does not prove a definitive decoupling.
Chainalysis's own methodology requires caution. Its measure of “crypto economy” combines inflows to services, domestic P2P transfers and certain international flows. Part of the geographic location is also estimated through behavioral indicators and web traffic. The company acknowledges that the metric is a conservative estimate and that not all on-chain activity can be correctly attributed to a country.
There is also a difference between transferring stablecoins and using them to buy goods or services in the real economy. A transfer between wallets may represent payment, remittance or savings, but may also be part of other financial strategies. The BIS and IMF continue to point to this difficulty of separating the apparently economic volume from activity linked to the crypto market itself.
Still, the 2025–2026 bear market produced a test that previous cycles had not shown with the same clarity. In 2023, a reduction of only US$ 300 billion in capitalization coincided with a 23% drop in activity measured by Chainalysis. This time, a destruction of US$ 2.1 trillion in market value was accompanied by a contraction of only US$ 100 billion in activity.
The next test will be to verify whether this divergence remains when market conditions change. The evolution of P2P in stablecoins, the size of international flows and, above all, the share that can be associated with payments, commerce, remittances and business operations will indicate whether an economic layer capable of crossing different price cycles is emerging.
For now, the data show a more limited but concrete change: the crypto market remains cyclical; part of the infrastructure built on top of it is beginning to not be.